Insights · November 9, 2026
Running Digital PR Across a Private Equity Portfolio
How private equity sponsors centralize digital PR across portfolio companies without burning journalist relationships or cannibalizing coverage between portcos.
By Samuel Edwards · Senior PR Strategist

How do you run digital PR across a private equity portfolio without burning the same journalists ten times or leaking the sponsor brand into every placement? Run one shared function with strict portfolio segregation: one data desk, one journalist CRM, separate editorial voices, and separate outreach queues per portco, with the sponsor name kept out of the pitch itself.
The operating question matters now because the book is bigger and held longer. PE firms completed 587 add-on acquisitions in Q1 2026, representing 54.2% of all PE deal activity, the highest add-on share in the trailing dataset. Communications sits downstream of that shift. Ad-hoc portco arrangements routed through separate agencies, often picked by individual portco CMOs, do not scale past roughly ten brands without introducing the three risks below. Sponsors trying to build their own in-house enterprise PR capability hit the same wall from the other side: cost per portco.
The Backlog That Forced Shared Operations
PE sponsors held 13,325 portfolio companies at the end of Q1 2026, and more than six in ten had been owned for four years or more. Hold periods have stretched past original underwriting assumptions, which means value-creation levers that compound over time (brand authority, search equity, LLM citation volume) matter more relative to the quick operational fixes that work in year one. EY's 2025 benchmark of 128 PE executives found nearly 85% of GPs expect AI to have a significant or transformational impact on their business within five years, while 70% report heightened focus on cost takeout. Centralizing PR across the book addresses both at once: it removes duplicate agency retainers and builds the cumulative earned-media footprint that generative engines actually learn from.
Not every portfolio is a candidate. A portco with a six-month hold and an imminent exit is not a compounding asset. The sponsor-shared model earns its cost on books that will live together for three or more years.
Three Risks That Break an Uncoordinated Portfolio
Three failure modes recur across sponsors running PR brand-by-brand. First, duplicate pitching. A reporter at a tier-one trade outlet gets a similar quarterly data trend from three portcos inside a month, each pitched in isolation, and starts routing mail from the whole book to the trash. Second, brand leakage. A portco CEO drops the sponsor name into a product-launch quote, a competitor connects the dots, and the capital relationships that should be invisible stop being invisible. Third, cannibalization. Two portcos pitch overlapping long-tail keywords in the same quarter, and the second one earns no incremental SEO lift because the first already took the links.
These problems scale non-linearly. At four portcos they are housekeeping. At fifteen they erode coverage, erode link equity, and complicate the LP conversation about whether the value-creation plan is actually running.
What Belongs in the Shared Function
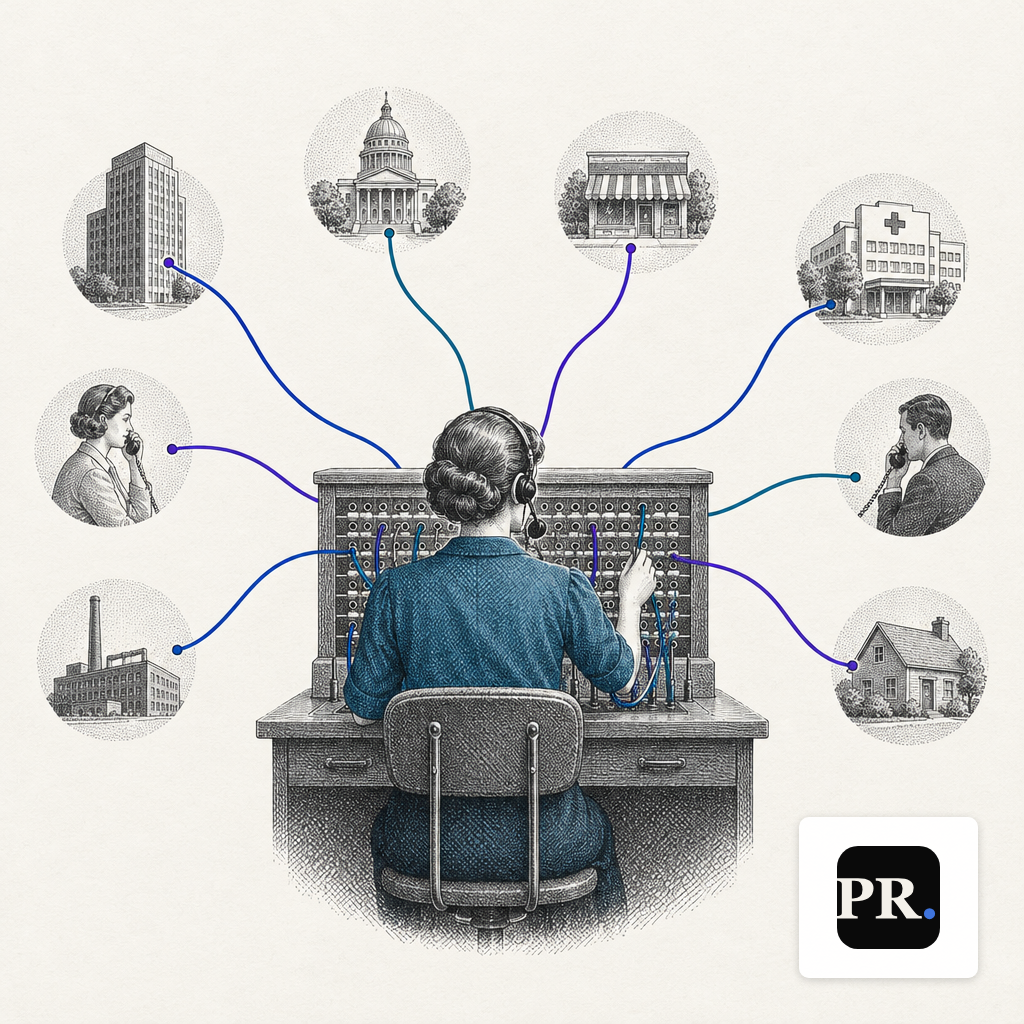
Infrastructure that compounds, and that is expensive to rebuild per portco, belongs at the sponsor level. A central PR operations unit should own four things:
- A journalist CRM with coverage history, embargo logs, and cross-portco conflict flags. The baseline setup is covered in the outreach CRM setup post.
- Reusable research infrastructure: a survey panel, methodology pages, and a legal review process any portco can draw on without rebuilding from scratch.
- A pitch calendar that staggers overlapping angles. Two portcos pitching the same data trend to the same reporter in the same month is both a dollar cost and a relationship cost.
- Measurement scaffolding: share of search, linking root domains, and AI citation share, reported per portco and per sector cohort rather than averaged across the book.
The journalist shortlist is where centralization pays back first. One desk sees every reporter every portco has pitched in the last eighteen months, so the next outreach lands with a fresh hand rather than the beat reporter who passed on a different portco last quarter. The process in how to build a journalist shortlist is a reasonable template for a shared desk to adapt per brand.
What Stays With the Portco
Centralization fails when it reaches into editorial voice. CEO quotes, embargo decisions on a product launch, crisis response, and the choice of which trade publication to prioritize all stay with the portco. Standardizing them produces coverage that reads like a shared-services press release, which is the fastest way to lose both journalist interest and portfolio-company buy-in.
The sponsor's name usually does not belong in the pitch itself. The 2026 Edelman Trust Barometer found more than four in ten respondents say what unpaid voices say about a brand has the biggest impact on their willingness to trust it, versus only 20% citing a brand's own communications. Earned credibility is the portco's own; a halo borrowed from the capital stack rarely holds up in the places that matter to buyers. Sponsor attribution belongs in the LP update, not the trade-press piece.
The Roll-Up Arithmetic Behind a Shared Desk
Sponsors fund any of this because the arithmetic of a roll-up rewards brand equity that transfers at exit. Platforms are acquired at one multiple, bolt-ons at a lower one, and the combined entity is sold at or above the platform multiple. Brand strength, search authority, and journalist familiarity are among the few assets a sponsor can genuinely build during ownership and extract at sale. The chart below shows the multiple arbitrage per dollar of bolt-on EBITDA at the low end of a typical PE roll-up structure.
Measuring the Book Without Mixing Scoreboards
Portfolio-level measurement is where sponsors get frustrated fastest. Three metrics behave differently across portcos and need to be read per brand before any rollup:
- Share of search. Hankins and Binet's cross-category research found share of search accounts for about 83% of a brand's market share and leads it by six to twelve months. Per-portco share of search is a leading indicator; a cross-portco average is mostly noise.
- Link equity. Google's John Mueller has said the company does not treat unlinked brand mentions as a direct ranking signal, with no signal passing the way a normal link does. Count linking root domains per portco, not mention volume, and never credit a sponsor-level mention to a portco page.
- AI citations. LLM citation share is where a shared data desk pays back visibly, because a single methodology page can be cited in Perplexity answers across three portcos. Benchmarks are in our review of AI search statistics.
When to Centralize and When Not To
The decision to run a shared PR function across a PE portfolio turns on three conditions. Centralize when the book contains more than ten portcos sharing journalist beats or competing for the same long-tail search terms, because the deconfliction cost of leaving each portco to pitch alone outweighs the loss of editorial independence. Centralize when expected holds exceed four years, because the compounding assets a central desk builds, from survey panels to journalist trust, mature on that horizon. Leave PR with the portco when the brand sits in a consumer category where sponsor association would actively depress trust, or when the hold is clearly under two years and no cumulative asset will mature in time to matter. Every other portfolio is a hybrid: shared infrastructure, portco voice, sponsor name off the pitch, and a digital PR engagement sized to the hold period rather than the current quarter.